Is Inflation a Blessing or a Curse?
Why everything feels so expensive, who wins and who loses from inflation, how a wage-price spiral and hyperinflation take hold, and how to beat inflation by choosing which side of it you stand on.
Is Inflation a Blessing or a Curse?
MAKE IT WORK FOR YOU
In April 2009, a shopper in Harare handed over a single banknote for two coconuts. The note read one
hundred trillion dollars. Six months earlier, a note with that many zeros on it would have been
unthinkable. A year before that, the currency it belonged to could still buy a car. Nothing happened to
the coconuts. Something happened to the money.
That's the extreme version of a mechanism most of us deal with every single week without ever
looking at it directly. Explanations of inflation almost always start with prices: the price of bread,
the price of petrol, the price of a house. That's back to front. Prices are just the symptom.
The actual disease is happening to the cash itself, quietly, in the background, whether or not anyone
in the room is discussing coconuts.
What Is Inflation?
The textbook definition is straightforward enough: inflation is the rate at which
the general level of prices for goods and services rises over time, which erodes the purchasing power
of money. If inflation runs at 5%, something that costs $100 today will cost roughly $105 a year from
now.
In practice, no two things inflate at the same rate, which is why economists lean on a
blended measure like the Consumer Price Index (CPI), a running tally of what a
representative basket of everyday goods and services actually costs consumers over time.
But
the more useful way to hold this idea in your head isn't "prices go up." It's
"cash goes down." Nothing about a loaf of bread changes when inflation rises. What changes is
how much your money can still buy of it. Once you start thinking about inflation as a slow leak in the
value of cash, rather than a slow climb in the cost of things, everything that follows starts making a
different kind of sense.
What Causes Inflation?
What causes inflation comes down to one of two things: too much money chasing too few goods, or the cost of producing those goods going up. Central banks printing money, supply shocks like oil price spikes, and strong consumer demand outpacing supply are the usual triggers. Zimbabwe's hundred-trillion-dollar note happened because the government printed money to cover its bills, not because coconuts got harder to grow.
Why Does Everything Feel So Expensive?
Ask most people why everything feels so expensive and they point at specific things: groceries, rent, petrol, insurance premiums. Each has its own story, but they are all riding the same current. When the value of cash falls, it falls against everything at once, so the effect turns up everywhere you spend at roughly the same time. That is why it feels less like a few things getting pricier and more like your money simply going less far.
Groceries feel the sharpest because you buy them every week, so you notice the change faster than on a bill that arrives once a year. The mechanism is identical. Nothing about the food changed. What changed is what your money is still worth by the time you reach the till.
The Winners and Losers of Inflation
The winners and losers of inflation aren't random: anyone holding debt at a fixed rate wins, because they repay it in cash worth less than when they borrowed it, while anyone holding cash loses as its buying power quietly erodes.
Alan Greenspan (born March 6, 1926) ran the US Federal Reserve from 1987 to 2006, and for
most of that time, Fed policymakers privately agreed on a target: keep inflation at around 2% a year. They didn't say so publicly, at Greenspan's own insistence. Two percent was treated less
as an announcement than a quiet operating assumption, low enough to avoid the risk of deflation, stable
enough that nobody had to think about it too hard.
Governments lean on interest rates to keep inflation near that number. Raise rates, and saving
gets more attractive while spending gets more expensive, which cools demand and, in theory, prices
along with it.
The conventional wisdom is that a little inflation, low, stable, predictable, is
actually a sign of a healthy economy, because it means the value of your investments and assets is
quietly rising while the real value of what you owe is quietly falling.
Notice the two
conditions buried in that sentence: investments, and what you owe. That policy only flatters you if
you're holding assets and holding debt. If you're sitting mostly in cash, with no
mortgage and no loan attached to anything, the exact same 2% that's making the property-owning,
mortgage-holding household better off every year is taking a small, silent bite out of you instead.
Same policy. Same number. Two completely different experiences, depending entirely on which side of the
ledger you happen to be standing on.
What Do the Numbers Show About Inflation?
Here's where it stops being theoretical. Say you borrow $100,000 from a bank at a fixed 5% over 25 years to buy a house. At the point of purchase you earn $36,000 a year, and your repayments run $585 a month. To see what inflation actually does to that arrangement, apply the same rate of inflation to both the value of the house and to your wage, and watch what happens to everyone in the deal, not just you.
3% Inflation for 7 years
| Year | House Price | Wages |
|---|---|---|
| Start | $100,000.00 | $36,000.00 |
| Year 1 | $103,000.00 | $37,080.00 |
| Year 2 | $106,090.00 | $38,192.40 |
| Year 3 | $109,272.70 | $39,338.17 |
| Year 4 | $112,550.88 | $40,518.32 |
| Year 5 | $115,927.41 | $41,733.87 |
| Year 6 | $119,405.23 | $42,985.88 |
At 3%, this is close to the textbook version of the miracle of compounding. Over seven years your house has risen in value by about 20%, your wages have risen by roughly the same amount, and your repayment hasn't moved at all. You are, in real terms, meaningfully ahead.
Look at it from the lender's side and the picture holds up too. They're earning 5% on money that's only losing 3% of its value a year, a real return of about 2%. Nobody in this transaction is losing. The borrower gets richer in real terms, the lender still comes out ahead of inflation, and the arrangement holds together because both sides are quietly winning, just at different rates. This is the version of inflation everyone is happy to talk about.
20% Inflation for 7 years
| Year | House Price | Wages |
|---|---|---|
| Start | $100,000.00 | $36,000.00 |
| Year 1 | $120,000.00 | $43,200.00 |
| Year 2 | $144,000.00 | $51,840.00 |
| Year 3 | $172,800.00 | $62,208.00 |
| Year 4 | $207,360.00 | $74,649.60 |
| Year 5 | $248,832.00 | $89,579.52 |
| Year 6 | $298,598.40 | $107,495.42 |
Now push the same mechanism further. At 20%, over the same seven years, your house has roughly tripled in value and so have your wages, while your repayment is still exactly $585 a month, a number that would have sounded serious in year one and sounds almost like a rounding error by year seven.
From where you're standing, this looks like the best deal in financial history. From the lender's side, it's a disaster: they're earning 5% on money that's losing 20% of its value a year, a real loss of about 15% annually. And lenders notice arithmetic like that just as quickly as borrowers do. They stop lending, or they demand rates nowhere near 5% before they'll try again, which means the next person who wants to buy a house, quite possibly you, a few years from now, can no longer get the deal you just got. The 20% world doesn't just cost the lender money. It quietly closes the door behind you.
It's only a win if everyone involved is winning, even if they're winning by different amounts. The moment one side of that trade starts losing badly enough, the trade stops happening for anyone.
For a longer view of the same mechanism, twenty years of inflation, interest rates and the share market side by side, see what happens to your money when the cost of living rises.
What Is the Problem with High Inflation? The Wage-Price Spiral
High inflation is hard to unwind once it takes hold, because it feeds itself. It generally starts when demand for goods or services outpaces supply. Wholesale prices rise, retail prices follow, wages have to rise to keep up with retail prices, and rising wages push costs up again for whoever's providing the services those wages get spent on. Economists call this self-reinforcing loop a wage-price spiral. While all of that is adjusting, it's a genuinely painful stretch for a lot of people, especially if your supermarket bill has jumped and your wages haven't caught up yet.
Governments have blunt tools here: raise the central bank's interest rate, or in extreme cases, print more money. Both come with trade-offs, which is exactly why a low, boring, controllable rate like 2% is the target almost every developed economy quietly agrees on. It's the version of inflation from the first table above, not the second one.
Most countries manage to stay somewhere near that equilibrium, most of the time. Some don't. And when a government loses its grip on this completely, rather than partially, drifting from the 3% story toward something far past the 20% one, this is roughly what it looks like.
Zimbabwe and the Anatomy of Hyperinflation
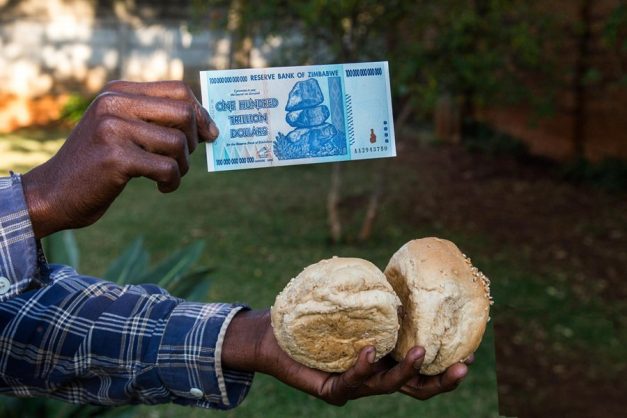
Hyperinflation is what economists call inflation running at more than roughly 50% in a single month, the point where money stops doing its job and people rush to spend it before it loses more value. Zimbabwe in the 2000s is the textbook case.
On the 18th of April 1980, Rhodesia became Zimbabwe. Two decades later, a set of policy decisions known as the Economic Structural Adjustment Programme (ESAP) drove food production down by roughly 45%, pushed unemployment up by around 80%, and shortened life expectancy across the population. Demand for food, goods, and basic services badly outstripped supply, and with a government unwilling or unable to change course, the result wasn't high inflation. It was hyperinflation, the same mechanism from the numbers above, except with every brake removed.
That's the note from the opening of this article: a hundred trillion dollars, handed over for two coconuts. It isn't a punchline. It's what the 20% scenario looks like once it stops being a worked example and starts being an entire country's actual currency.
How to Beat Inflation: Make It Work for You
You can't personally set the inflation rate, but you can decide which side of it you're standing on, and that decision is almost entirely within your control.
- Own things that tend to rise with inflation. Gold and real estate have historically held up well over long stretches. That said, don't overestimate your own skill at picking investments, the boring, slow, unglamorous option is often the safer one, and every investment carries some cost to hold, so know what that cost is before you commit to it.
- Don't sit on more cash than you need. Cash is the one asset inflation is guaranteed to erode, so hold enough to stay comfortable and no more. At the same time, remember that governments often raise interest rates to fight inflation, so make sure you could handle higher repayments if they do, either by keeping a cash buffer on hand or by fixing your rate in advance. Just be careful not to fix a rate you couldn't actually afford if it moved.
- Manage your money well enough to still enjoy it. None of this is really about hoarding against some imagined future. Life is for living, and the point of positioning yourself sensibly against inflation is to be able to afford both the investments and the life, not to trade one for the other.
Inflation itself doesn't reward or punish anyone directly. It just quietly amplifies whatever position you were already in when it arrived, and almost nobody ends up well positioned by accident.
Inflation: Common Questions
Is inflation good or bad?
Neither on its own. A low, steady rate near 2% quietly helps anyone holding assets and debt, and quietly costs anyone sitting in cash. High or unstable inflation hurts almost everyone, because it breaks the arrangements people rely on, like being able to borrow to buy a house.
Does inflation reduce your debt?
It reduces the real weight of a fixed-rate debt. The repayment stays the same in dollar terms while wages and prices rise around it, so over time it takes a smaller share of your income. Variable-rate debt does not get this benefit, because the rate rises with inflation.
How does inflation affect your savings?
Cash savings lose purchasing power at roughly the inflation rate every year. Holding some cash for security is sensible, but money you do not need soon is slowly shrinking in real terms while it sits there.
What is a wage-price spiral?
A feedback loop where rising prices push workers to seek higher wages, higher wages raise business costs, and those costs push prices up again. It is one of the main reasons high inflation is hard to stop once it starts.
Further Reading
 BlogHow Much Should I Have in My Rainy Day Fund?The three-to-six-months rule is a number for an average person who does not exist. How to size a rainy day fund from your own risks, and why the fund is only one of three defences.Read article
 SolutionThe Cost of Living Squeeze and How You Might Come Out on TopPrices keep climbing, and you can't control that. What you can control is surviving the squeeze with real numbers instead of guesswork, and even coming out ahead of it, while everyone else just absorbs the hit.Explore solution
 BlogCash Is King: Cash Flow vs Net WorthCash is king, but not for the reason the phrase usually implies. Why cash flow, not net worth, is what actually keeps you solvent.Read article
Disclaimer: We are not financial advisers. The information on this website is general in nature and does not take into account your individual circumstances. You should seek independent professional advice before making financial decisions.